Understanding Comparative Negligence in Accident Claims
Comparative negligence can reduce your accident settlement by thousands. Know how fault is divided and how to protect your recovery.
By Amaris Quinn
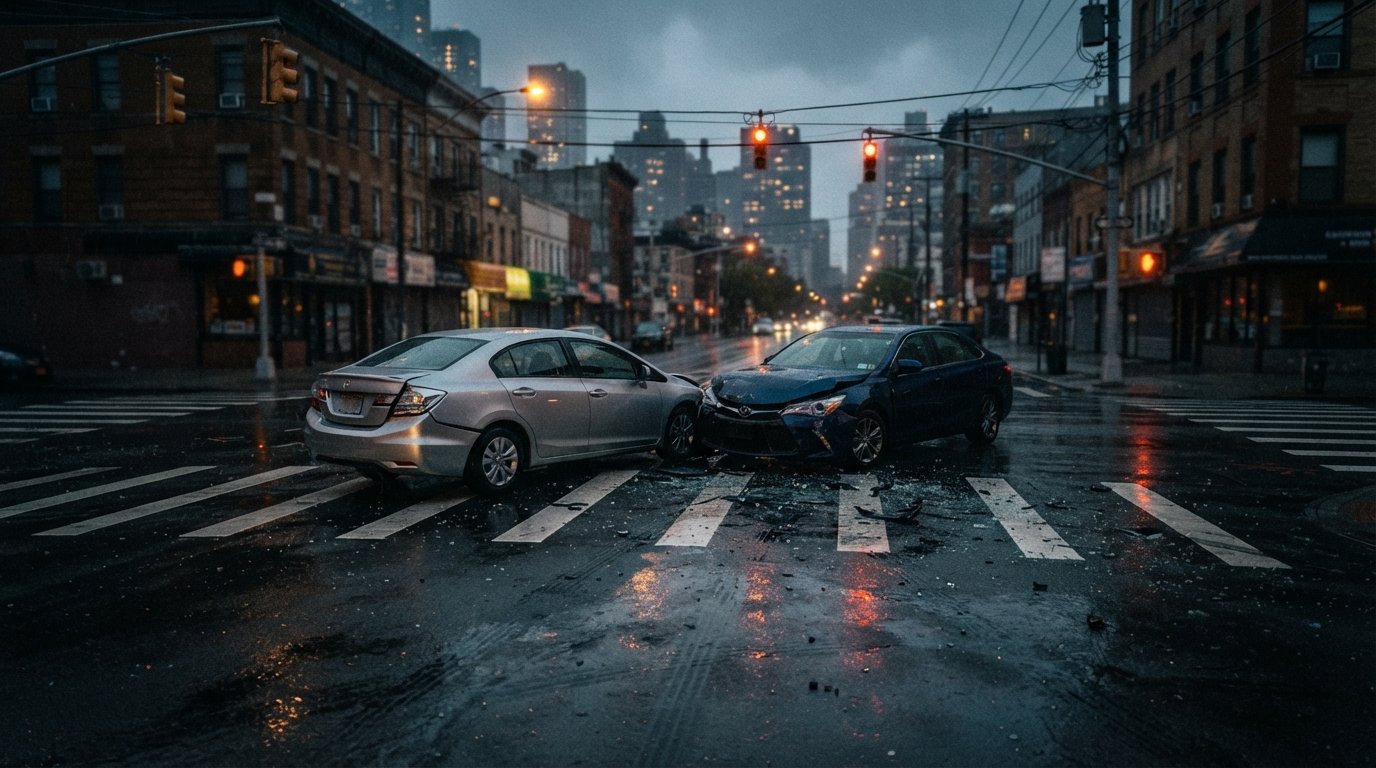
You are driving through an intersection when another car clips your rear bumper. Your neck snaps forward, your car spins, and suddenly you are facing medical bills, repair costs, and lost wages. Then the insurance adjuster calls and says something that makes your stomach drop: "Our driver says you were speeding too, so we are only paying part of your claim." That single sentence introduces one of the most misunderstood concepts in personal injury law: comparative negligence.
The idea that your own actions could reduce your recovery feels unfair, especially when the other driver clearly ran a red light or rear-ended you. But comparative negligence rules govern how fault gets divided in accident claims across most of the United States, and those rules directly affect how much money ends up in your pocket. Understanding how this system works, how insurers use it against claimants, and what you can do to protect your recovery is essential before you accept any settlement offer.
What Comparative Negligence Actually Means in an Accident Claim
Comparative negligence is a legal doctrine that allocates fault between parties when an accident occurs. Instead of treating every accident as a simple case of one person being entirely right and the other entirely wrong, comparative negligence recognizes that multiple people can share responsibility. If you were 20 percent at fault for a car crash and the other driver was 80 percent at fault, your total damages get reduced by your percentage of fault.
This concept exists because real-world accidents rarely happen in a vacuum. Maybe you were driving five miles over the speed limit when someone turned left in front of you. Maybe you were distracted for a split second before a rear-end collision. Maybe you failed to use a turn signal while changing lanes, and another driver swerved into you. These contributing factors do not erase the other party's negligence, but they can reduce your financial recovery.
The practical effect is significant. Suppose a jury determines your total damages are $100,000. If you bear 30 percent of the fault, you receive $70,000. If you bear 60 percent of the fault in a state that follows pure comparative negligence, you still recover $40,000, just less of it. The math matters enormously, and insurance companies know it.
If you want a deeper walkthrough of how these rules apply specifically to vehicle collisions, our guide on what is comparative negligence in a car accident claim breaks down the scenarios where fault disputes arise most often.
The Three Main Systems States Use to Divide Fault
Not every state handles comparative negligence the same way. The legal landscape breaks down into three broad approaches, and knowing which system applies to your claim shapes everything from settlement negotiations to trial strategy.
The first is pure comparative negligence. Under this system, you can recover damages even if you are 99 percent at fault, though your recovery gets reduced by your percentage of responsibility. Only a handful of states follow this approach, but it is the most forgiving for injured claimants who share significant fault.
The second is modified comparative negligence, which comes in two variations. In the 51 percent bar version, you cannot recover anything if you are found 51 percent or more at fault. In the 50 percent bar version, you cannot recover if you are 50 percent or more at fault. Most states use some form of modified comparative negligence because it balances fairness to injured parties with a limit on claims by people who bear most of the responsibility.
The third is contributory negligence, which is the harshest rule. Under pure contributory negligence, if you are even 1 percent at fault, you recover nothing. Only a few jurisdictions still follow this rule, but if you live in one of them, even a minor mistake on your part could eliminate your entire claim.
Here is a quick comparison of how the same accident would play out under each system:
- Pure comparative negligence: You are 80 percent at fault, so you recover 20 percent of your damages.
- Modified comparative negligence (51 percent bar): You are 80 percent at fault, so you recover nothing because you exceeded the threshold.
- Modified comparative negligence (50 percent bar): You are 50 percent at fault, so you recover nothing because you hit the threshold exactly.
- Contributory negligence: You are 5 percent at fault, so you recover nothing at all.
These differences explain why accident claims that seem nearly identical can produce dramatically different outcomes depending on where they are filed. An attorney who understands your state's specific rules can structure your claim to minimize the fault attributed to you.
How Insurance Adjusters Use Comparative Negligence Against You
Insurance companies are not neutral parties. Their goal is to pay as little as possible on every claim, and comparative negligence gives them a powerful tool to reduce or deny payouts. Adjusters are trained to look for any fact that suggests you contributed to the accident, then use that fact to justify a lower offer.
Common tactics include exaggerating your speed, claiming you should have seen the other vehicle coming, arguing that you failed to take evasive action, or suggesting that your injuries were pre-existing. Even minor details like the condition of your tires, whether your headlights were on, or whether you had consumed any medication can become ammunition in a fault dispute.
What makes this especially frustrating is that adjusters often raise comparative negligence arguments without solid evidence. They rely on the assumption that you will accept a reduced offer rather than fight for full compensation. If you do not push back with evidence and legal reasoning, you leave money on the table.
Steps to Counter a Fault Allegation
When an insurer claims you share fault, you can take specific steps to protect your claim. Gathering evidence quickly and documenting your version of events strengthens your position significantly.
- Obtain the police report and review what the officer concluded about fault.
- Collect witness statements from anyone who saw the accident.
- Take photos of the scene, vehicle damage, and any relevant road conditions.
- Preserve medical records that document the timing and severity of your injuries.
- Consult an attorney who can challenge unsupported fault allegations with legal authority.
Each of these steps builds a record that makes it harder for an adjuster to justify shifting blame onto you. The earlier you act, the more evidence remains available and the stronger your negotiating position becomes.
Evidence That Determines Fault Percentages
Fault allocation is not guesswork. It relies on evidence that either supports or undermines claims about what happened. The quality of that evidence often determines whether you recover 90 percent of your damages or 60 percent.
Police reports carry significant weight because officers are trained to assess fault at the scene. However, police reports are not binding, and they can contain errors or incomplete information. Witness testimony adds another layer, especially when independent witnesses corroborate your account. Physical evidence, including skid marks, vehicle damage patterns, and traffic camera footage, can be decisive.
Medical records also play a role in comparative negligence disputes, particularly when insurers argue that your injuries were caused by something other than the accident. Consistent medical treatment and clear documentation of symptom onset help rebut those arguments.
In some cases, accident reconstruction experts are brought in to analyze the physics of a collision and determine speeds, angles, and reaction times. These experts can be expensive, but their testimony often shifts the fault percentage in meaningful ways.
What Happens When Fault Is Disputed
When you and the insurance company disagree about fault, the dispute can escalate through several stages. Initially, your attorney negotiates directly with the adjuster, presenting evidence and legal arguments to support a lower fault percentage for you. If that fails, the case may proceed to mediation, where a neutral third party helps both sides reach a compromise.
If mediation does not resolve the dispute, litigation becomes the next step. A judge or jury ultimately decides how to allocate fault, and their decision is based on the evidence presented at trial. This process can take months or years, and it introduces uncertainty for both sides.
Because of that uncertainty, many cases settle before trial even when fault is contested. Insurers know that a jury could assign them a higher percentage of fault than they want, and claimants know that a jury could assign them more fault than they expect. This mutual risk creates incentives to compromise.
Understanding how fault disputes resolve helps you make informed decisions about settlement offers. An offer that seems low might actually reflect a realistic assessment of your fault percentage, while an offer that seems generous might come with hidden strings attached.
How Comparative Negligence Affects Settlement Value
Your settlement value is not just your total damages. It is your total damages multiplied by the other party's percentage of fault. If your medical bills, lost wages, and pain and suffering add up to $200,000, and you are 25 percent at fault, your claim is worth $150,000 before considering other factors like policy limits and available insurance coverage.
This calculation explains why insurers fight so hard over fault percentages. Every percentage point they shift onto you reduces their payout. A 10 percent shift on a $200,000 claim saves them $20,000, which is more than enough motivation to hire investigators and experts.
It also explains why you should never accept a fault allocation without scrutinizing the evidence behind it. Adjusters sometimes propose fault percentages that have no basis in the actual facts, hoping you will not challenge them.
Special Rules for Different Types of Accident Claims
Comparative negligence rules apply broadly, but some claim types have unique considerations. In premises liability cases, for example, property owners may argue that you ignored warning signs or failed to watch where you were walking. In product liability cases, manufacturers may claim you misused their product or ignored safety instructions. In medical malpractice cases, defendants may argue that your own health decisions contributed to your outcome.
Each of these scenarios requires a tailored approach. The evidence that rebuts a fault allegation in a car accident case differs from the evidence needed in a slip and fall case. Working with an attorney who understands the specific dynamics of your claim type is essential.
Why Legal Guidance Matters in Comparative Negligence Cases
Comparative negligence introduces complexity that most injured people are not equipped to handle alone. Insurance adjusters deal with these issues daily, and they know how to exploit uncertainty. Without legal representation, you may accept a reduced settlement that does not reflect the true value of your claim.
An experienced attorney can investigate the accident, gather evidence, challenge unsupported fault allegations, and negotiate from a position of strength. If litigation becomes necessary, your attorney can present your case to a jury and argue for a fair fault allocation.
For individuals who are unsure whether they have a viable claim, platforms like FreeLegalCaseReview offer free case evaluations that connect accident victims with qualified personal injury attorneys. These evaluations help you understand your rights and options without any upfront cost or obligation.
The bottom line is that comparative negligence does not have to destroy your claim. With the right evidence, legal strategy, and representation, you can minimize the fault attributed to you and maximize your recovery. Do not let an insurer's fault allegation become an excuse to underpay you. Take action early, document everything, and get the legal guidance you need to protect your financial future.