What Is a Demand Letter in a Personal Injury Case?
A demand letter in a personal injury case formally asks an insurer to pay for your injuries and losses. Learn what it includes and why it shapes your settlement.
By Melissa Hughes
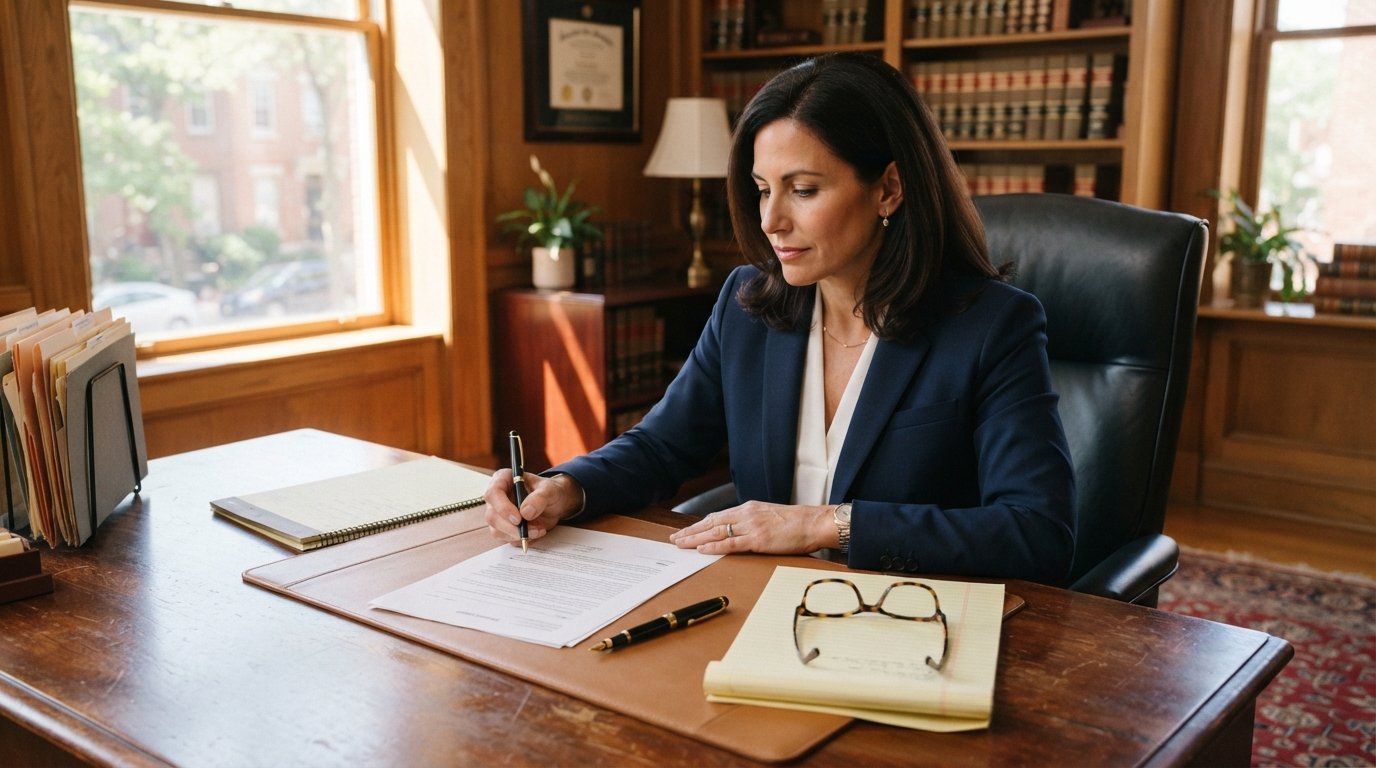
If you have been injured in an accident and your attorney has started talking about a demand letter, you may be wondering exactly what that document does and why it matters so much. In simple terms, a demand letter in a personal injury case is a formal, written request sent to the at-fault party or their insurance company that explains the accident, details your injuries and losses, and asks for a specific amount of money to resolve your claim. It is often the single most important piece of communication in the entire pre-litigation phase, and how it is written can heavily influence what you ultimately recover.
Long before a lawsuit is ever filed, most personal injury claims are resolved through negotiation. The demand letter is the opening statement of that negotiation. It tells the insurer who you are, what happened, why their insured is responsible, and what it will cost them to make things right. A well-crafted demand letter backed by solid evidence can pressure an insurer to make a fair offer quickly, while a weak or rushed letter can lead to lowball offers and months of unnecessary back-and-forth. Understanding this document helps you participate more confidently in your own case and ask better questions of your attorney.
What Exactly Is a Demand Letter in a Personal Injury Case
A demand letter is a formal written document, usually prepared by your personal injury attorney, that is sent to the insurance adjuster or the responsible party after you have finished treating for your injuries. It is not a lawsuit, and it does not automatically start a court case. Instead, it is a settlement tool: it lays out the facts of the accident, the legal basis for the other party's liability, the full extent of your damages, and a specific dollar amount you are willing to accept to settle the claim.
The letter serves several purposes at once. It puts the insurer on notice that you are represented and that you are serious about pursuing compensation. It creates a written record of your version of events and your injuries. It also gives the adjuster everything they need to evaluate the claim, which often speeds up the process because the insurer does not have to chase down basic information. Finally, it sets the anchor for negotiations, since the first number on the table tends to shape everything that follows.
In most personal injury cases, the demand letter is sent after you have reached maximum medical improvement or finished active treatment. Sending it too early, before your injuries and future care needs are clear, can lock you into a number that does not reflect your true losses. That is one reason the timeline of a case matters so much; if you want to see how the demand letter fits into the broader progression of a claim, our guide on your personal injury case timeline walks through each stage from filing to resolution.
What a Demand Letter Typically Contains
Every demand letter is tailored to the specific accident, injuries, and jurisdiction, but most follow a similar structure. The goal is to tell a complete, persuasive story that leaves the adjuster with little room to dispute the key facts. A strong letter is organized, factual, and supported by documents rather than emotion, even when the underlying events were traumatic.
Most demand letters include the following core sections:
- Header and identifying information: Your name, the claim number, the date of the accident, the insured party, and the adjuster's contact details.
- Facts of the accident: A clear narrative of how the injury happened, who was involved, and why the other party was at fault.
- Liability argument: An explanation of the legal duty the other party owed you and how they breached it, often citing police reports, witness statements, or traffic laws.
- Injuries and medical treatment: A chronological account of your diagnosis, treatment, providers, and current prognosis.
- Damages breakdown: Itemized medical bills, lost wages, out-of-pocket costs, and a request for pain and suffering or other non-economic damages.
- Settlement demand: A specific dollar figure, sometimes with a deadline for response.
Attached to the letter, or referenced within it, you will usually find supporting evidence such as medical records, billing statements, police reports, photographs of the scene and injuries, wage loss documentation, and expert opinions. This evidence packet is what transforms a demand letter from a simple request into a persuasive settlement tool. Insurers are far more likely to take a demand seriously when every dollar claimed can be traced to a document.
Why the Demand Letter Matters So Much in Negotiations
The demand letter is often the first time the insurance company sees a fully organized picture of your claim. Before that point, the adjuster may only have a brief incident report and a few scattered medical bills. The demand letter consolidates everything into one narrative, which makes it easier for the insurer to evaluate risk and assign a settlement value. A clear, well-supported letter can move a claim toward resolution in weeks rather than months.
The number you demand also matters strategically. Set it too low, and you leave money on the table because the insurer will rarely offer more than the anchor you provide without heavy pushback. Set it unreasonably high with no supporting evidence, and you risk damaging your credibility, which can make the adjuster skeptical of even legitimate expenses. Experienced attorneys calibrate the demand to the facts, the venue, and the insurer's typical behavior in similar cases.
Timing is another critical factor. If you send a demand letter before you have finished treatment, the insurer may try to settle quickly for an amount that does not account for future surgery, ongoing therapy, or permanent limitations. Waiting until your medical picture is stable allows your attorney to include future medical costs and a more accurate pain and suffering figure. This is also the stage where a free case evaluation can be valuable if you have not yet hired counsel; platforms such as FreeLegalCaseReview connect injured people with attorneys who can assess whether a demand letter is appropriate and what it should include.
How a Demand Letter Fits Into the Settlement Process
Once the demand letter is sent, the insurer typically responds in one of three ways: it accepts the demand, it makes a counteroffer, or it denies liability altogether. Most commonly, the adjuster responds with a counteroffer that is significantly lower than your demand. From there, your attorney negotiates back and forth, providing additional documentation as needed, until both sides agree on a number or the case reaches an impasse.
If negotiations fail, the next step is usually filing a lawsuit. Even then, the demand letter remains useful because it becomes part of the case file and can be referenced during discovery or mediation. In some jurisdictions, a formal demand or offer of judgment can even affect who pays certain costs if the case goes to trial. That is why the letter should be written with an eye toward litigation, not just a quick settlement.
It is also important to understand that a demand letter is not a guarantee of payment. Insurers can and do dispute liability, argue that your injuries were pre-existing, or claim that your medical treatment was excessive. A strong demand letter anticipates these arguments and addresses them up front with evidence. The more thoroughly your attorney rebuts potential defenses in the letter itself, the less room the insurer has to reduce your settlement later.
Common Mistakes That Weaken a Demand Letter
Not all demand letters are created equal, and some mistakes can seriously undermine your claim. One of the most common is sending the letter before treatment is complete, which can result in a settlement that does not cover future care. Another is failing to document lost wages, out-of-pocket expenses, or property damage, all of which are recoverable in most personal injury cases but easy to overlook.
Other frequent problems include:
- Exaggerating injuries or inflating damages without evidence, which damages credibility.
- Omitting prior injuries or pre-existing conditions that the insurer will discover anyway.
- Using emotional or threatening language instead of a factual, professional tone.
- Failing to include a deadline or clear response instructions.
- Sending the letter to the wrong party or without proof of delivery.
Each of these issues gives the adjuster a reason to discount your claim or delay a response. A carefully drafted letter avoids these pitfalls by staying factual, complete, and well-organized. If you are handling your claim without an attorney, it is worth having a legal professional review your letter before you send it, since even small wording changes can affect how the insurer responds.
Frequently Asked Questions About Demand Letters
Do I need a lawyer to send a demand letter?
You are not legally required to have an attorney, and some people do send demand letters on their own. However, personal injury law involves complex rules about liability, damages, and deadlines, and insurers routinely treat unrepresented claimants differently than represented ones. An attorney can identify damages you might miss, such as future medical costs or loss of earning capacity, and can negotiate from a stronger position.
How long does it take to get a response?
Insurers typically respond within 30 to 60 days, though some take longer if the claim is complex or if they request additional documentation. If the demand includes a deadline, the adjuster may respond sooner. If no response comes, your attorney can follow up or proceed with filing a lawsuit.
Can I send a demand letter before I finish treatment?
You can, but it is usually not advisable. Sending a demand before your injuries are stable risks undervaluing your claim, especially if you may need future surgery or ongoing care. Most attorneys wait until you have reached maximum medical improvement or your doctor has provided a final prognosis.
What happens if the insurer ignores my demand letter?
If the insurer does not respond or refuses to negotiate, your options include sending a follow-up demand, filing a complaint with the state insurance department, or filing a lawsuit. In litigation, the demand letter can become evidence that you attempted to resolve the claim in good faith.
Getting Help With Your Demand Letter
A demand letter is more than a formality; it is the foundation of your settlement negotiation and often the difference between a fair recovery and a disappointing one. Whether you are still deciding whether to hire an attorney or you simply want a second opinion on your claim, understanding what the letter does and how it is built helps you make better decisions about your case.
If you have been injured and are not sure where to start, a free, no-obligation case evaluation can clarify your options and connect you with an attorney who handles claims like yours. LegalCaseReview provides educational resources and a patented attorney selection process designed to help injured people find qualified representation without upfront cost. Taking that first step can put you in a much stronger position when it comes time to send your demand letter and pursue the compensation you deserve.