What to Say to an Insurance Adjuster After a Car Accident
Knowing what to say to an insurance adjuster after a car accident protects your claim from day one. Use these scripts to avoid costly mistakes.
By Rohan Verma
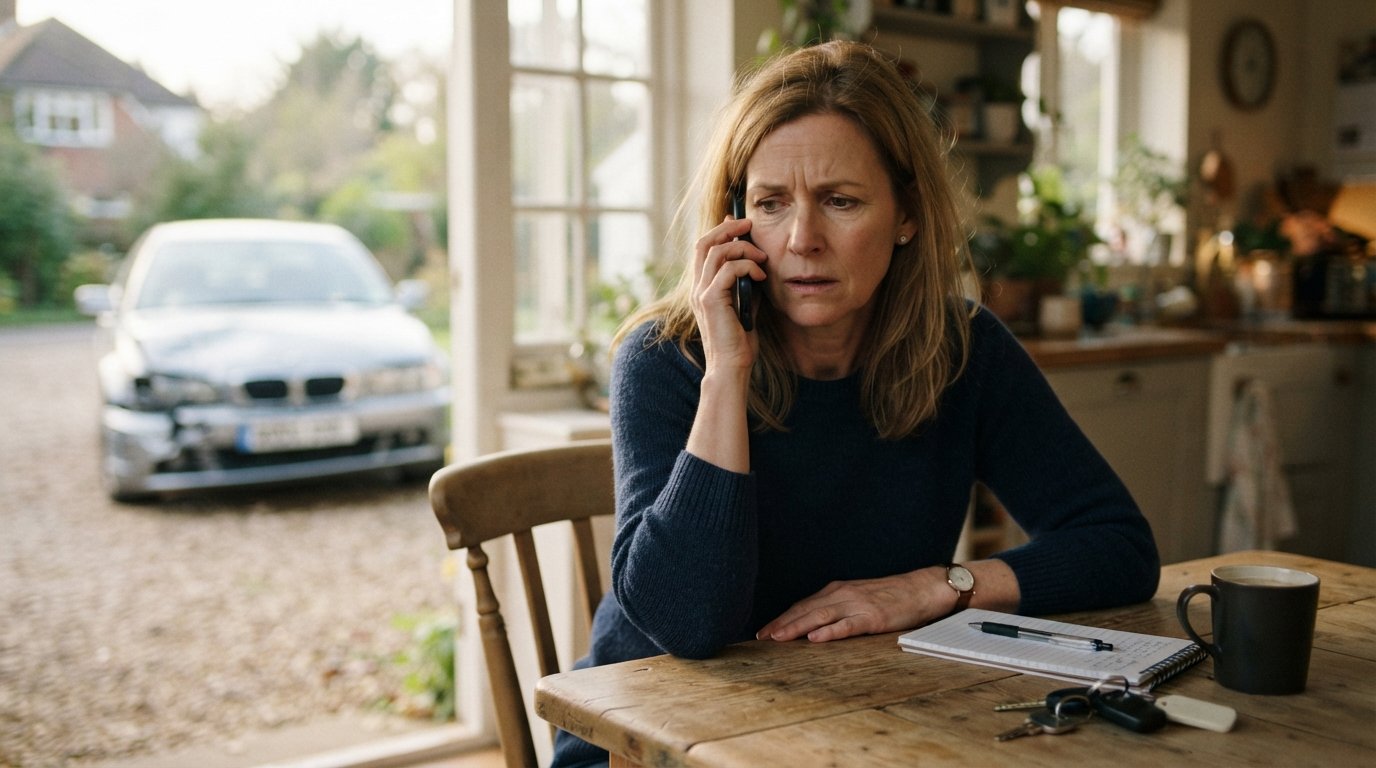
The phone rings two days after the crash. A friendly voice introduces herself as an insurance adjuster and asks how you are feeling. She sounds helpful, almost caring. Then come the questions: Was the light green? How fast were you going? Have you seen a doctor yet? Every answer you give becomes part of a recorded statement that the insurer will use to value, or devalue, your claim. What you say to an insurance adjuster after a car accident can matter as much as the medical treatment you receive in the days that follow.
Adjusters are trained professionals. Their job is to gather information, control the narrative, and settle claims for as little as possible. That does not mean you should refuse to cooperate or treat every call as a trap. It means you should prepare, keep your answers narrow, and understand which phrases protect your rights and which ones quietly undermine them.
Why Your Words Carry So Much Weight
After a collision, the at-fault driver's insurer typically opens a claim within days. The adjuster assigned to your file has two goals: confirm liability and minimize payout. Everything you say is documented, often verbatim, and can be compared later against police reports, medical records, and witness statements. A single careless remark, such as "I think I might have been speeding" or "honestly, I feel fine," can reduce a settlement offer by thousands of dollars.
There is also a timing problem. Many injuries, including whiplash, soft tissue damage, and concussions, do not fully surface for days or even weeks. If you tell an adjuster you feel okay the morning after the crash, the insurer will argue later that your injuries must be minor or unrelated. That early statement can follow you through the entire claims process, including negotiations and, if necessary, litigation.
Understanding the broader stakes helps too. If a dispute escalates and a case goes to court, the outcome can shape your financial future for years. Our analysis of what happens if you lose a car accident lawsuit explains the key outcomes, from owing the other side's costs to facing a counterclaim, so you can see why careful communication from day one is worth the effort.
What to Say to an Insurance Adjuster After a Car Accident: Core Scripts
You do not need to memorize a long script. You need a handful of calm, professional responses that keep the conversation factual and limited. The adjuster may push for detail, but you are never obligated to answer every question on the first call. Below are phrases that work in the most common situations.
- When asked for a recorded statement: "I am not prepared to give a recorded statement right now. I am happy to provide my contact information and cooperate with the investigation in writing."
- When asked how the accident happened: "The police report contains the details of the collision. I have nothing to add beyond what is documented there."
- When asked about your injuries: "I am still being evaluated by my doctors. I will not know the full extent of my injuries for some time."
- When asked if you were at fault: "I cannot speculate about fault. That is something the investigation will determine."
- When asked about prior accidents or conditions: "My medical history is private. My attorney can address any relevant records through the proper process."
Notice the pattern: polite, brief, and non-committal. You are not being rude or evasive. You are declining to guess, speculate, or characterize facts you do not yet fully know. Adjusters respect a claimant who stays composed and consistent, and recorded statements given too early are one of the most common ways injury victims unintentionally damage their own claims.
After any call, write down the date, the adjuster's name, and a short summary of what was discussed. If the adjuster sends a follow-up email, keep it. This paper trail protects you if the insurer later mischaracterizes the conversation.
What You Should Never Say to an Adjuster
Some statements are almost guaranteed to hurt your claim. The adjuster may seem sympathetic, and the conversation may feel casual, but treat every exchange as if it will be read aloud in a negotiation room, because it may be. Avoid these traps:
- "I am sorry" or "It was my fault." Apologizing is polite in daily life but reads as an admission of liability in a claim file.
- "I feel fine" or "It is just a little soreness." Injuries evolve. An early "I am fine" becomes ammunition against you later.
- Guessing at speed, distance, or timing. Estimates like "maybe 40 miles per hour" can be wrong and used to challenge your credibility.
- Speculating about the other driver. Comments about whether the other driver was distracted or drinking are for investigators, not claimants.
- Discussing your insurance limits or finances. These details are not the adjuster's business and can shape how the insurer values your claim.
- Accepting a quick settlement on the first call. Early offers rarely reflect the full value of a claim, especially before treatment is complete.
There is one more phrase to avoid: "I will just handle this myself." Many people say it out of frustration or a desire to save on attorney fees. In reality, injury victims who negotiate without guidance often settle for far less than their claim is worth, and the gap frequently exceeds what an attorney would have charged. If you are unsure whether you need representation, request a free case evaluation before you talk numbers with any insurer.
How to Handle Common Adjuster Tactics
Adjusters use predictable techniques to test claimants. One is the friendly early call, designed to catch you off guard before you have spoken with anyone about your rights. Another is the quick lowball offer, presented as a generous gesture that will disappear if you do not act fast. A third is the request for a recorded statement, framed as a routine step that is actually a tool for locking you into an early version of events.
When you recognize these tactics, they lose much of their power. You can slow the conversation down, ask for questions in writing, and decline to commit to anything on the spot. It is entirely reasonable to say, "I would like to review this with someone before I respond." Insurers deal with represented and unrepresented claimants every day, and they know that a careful claimant is harder to pressure.
If the insurer becomes aggressive, repeats calls, or misstates your words, document everything. In some cases, a pattern of bad-faith conduct can support a formal complaint or even a separate claim. Platforms such as LawyerOffer help injury victims understand their options and connect with attorneys who handle insurance disputes, which can be valuable when an adjuster crosses the line from negotiation into intimidation.
When to Stop Talking and Involve a Lawyer
There is no rule that says you must handle an adjuster alone. In fact, the moment a claim involves serious injuries, disputed fault, or a low settlement offer, professional guidance usually pays for itself. Attorneys know how insurers value claims, what documentation strengthens a demand, and when a case is worth filing in court. They also handle the adjuster calls so you can focus on recovery.
Consider legal help if any of the following apply to your situation:
- You were treated in an emergency room or have ongoing medical care.
- The insurer denies fault or disputes the severity of your injuries.
- You have lost wages or cannot return to your normal work.
- The adjuster asks for a recorded statement or pushes a fast settlement.
- You are unsure what your claim is actually worth.
Even if you ultimately decide not to hire an attorney, a free consultation gives you a clearer picture of the process and the likely value of your case. That knowledge changes how you speak to the adjuster, because you are no longer guessing.
Building a Paper Trail That Supports Your Claim
What you say is only half the equation. What you can prove matters just as much. From the first call with the adjuster, start assembling a simple file: the police report number, the other driver's insurance information, photos of the vehicles and the scene, contact details for witnesses, and every medical record and bill related to the crash. Keep a log of each adjuster conversation with dates and key points.
This documentation does two things. It keeps your account consistent, which protects your credibility, and it gives any attorney you consult a ready-made picture of the case. Insurers respond to organized claimants because organized claimants are harder to lowball. A calm voice on the phone plus a well-kept file is a combination that quietly strengthens every settlement demand you make.
Finally, remember that the adjuster is not your adversary as a person, but the role exists to protect the insurer's bottom line. You can be courteous and cooperative while still being careful. Say less, confirm only what you know, and let the evidence speak for the rest. If you ever feel outmatched, pause the conversation and get advice before you continue. The words you choose in those first few calls can shape your recovery for months or years to come.