Bankruptcy Impact on Mortgage and Car Loans in Pennsylvania
Bankruptcy impact on mortgage and car loans in Pennsylvania can be managed. Call (833)-279-1850 for a free case review and protect your home and car.
By Maribel Frost
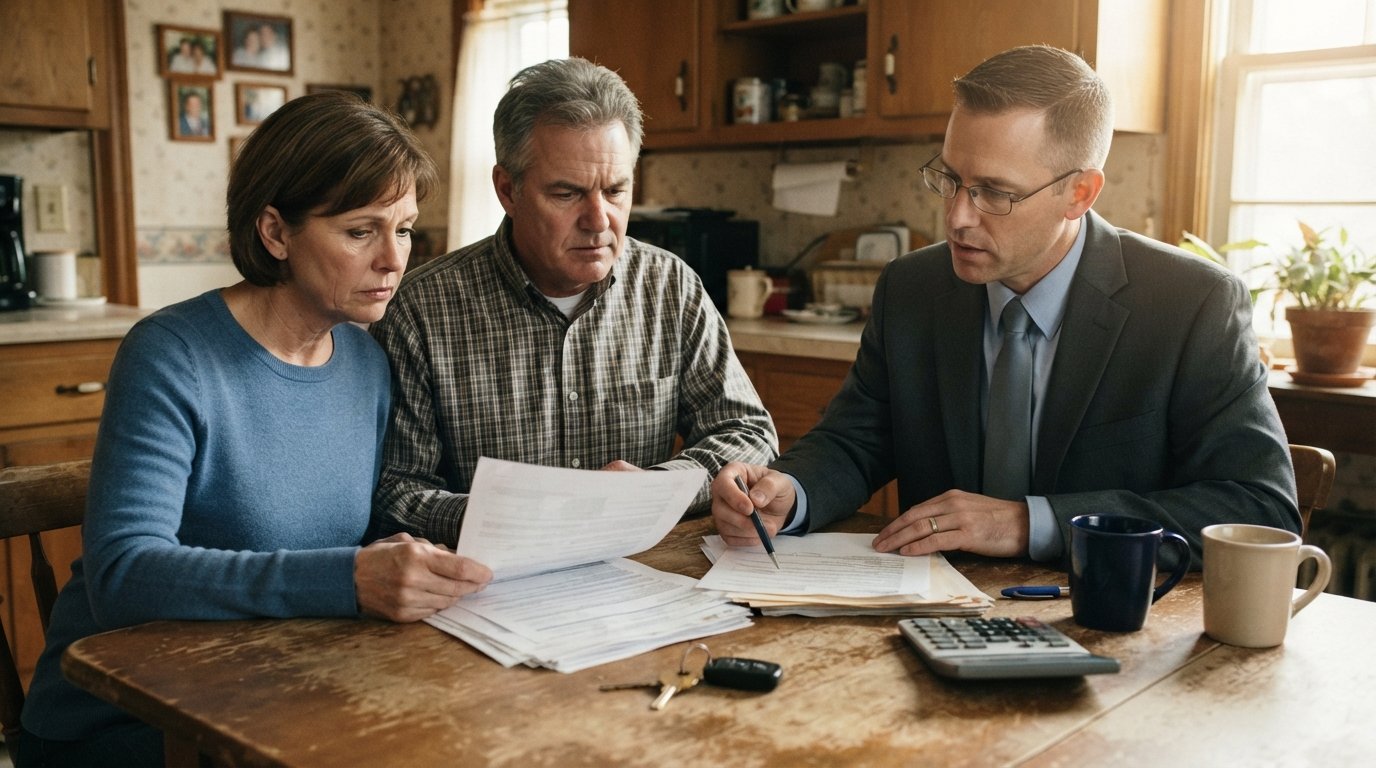
Filing for bankruptcy is one of the most consequential financial decisions you can make, and if you own a home or a car in Pennsylvania, the stakes feel even higher. You are likely asking a very specific question: will I lose my house or my vehicle if I file? The short answer is that bankruptcy does not automatically take your property. Instead, it reshapes how your secured debts are handled, and the outcome depends on the chapter you file, the amount of equity you hold, and the choices you make after your case begins. Understanding the impact of bankruptcy on mortgage and car loans in Pennsylvania requires a close look at state exemption rules, federal bankruptcy procedure, and the practical timeline that governs foreclosure and repossession. This article walks through those mechanics so you can evaluate your options with clarity.
How Pennsylvania Bankruptcy Law Treats Secured Debts
Pennsylvania does not allow debtors to use the federal bankruptcy exemptions. Instead, the state has its own set of exemptions, and those rules determine how much home equity and vehicle value you can protect. For a primary residence, Pennsylvania protects equity up to $35,300 under the state homestead exemption, with a higher threshold for certain protected persons such as surviving spouses. For a vehicle, the state exemption is $300, though married couples filing jointly can each claim that amount if they co-own the car. These numbers are modest, which means many Pennsylvania filers must rely on other strategies to keep their secured property.
The key concept is that a mortgage or car loan is a secured debt. The lender holds a lien against the property itself. When you file bankruptcy, the automatic stay immediately stops foreclosure sales, repossession, and collection calls. That breathing room is powerful, but it does not erase the lien. To keep the asset long term, you must either continue paying the loan, catch up on missed payments through a repayment plan, or use a specific legal tool such as reaffirmation or redemption. The impact of bankruptcy on mortgage and car loans in Pennsylvania therefore depends less on the filing itself and more on how you handle the secured debt after the automatic stay takes effect.
Chapter 7 Versus Chapter 13: Two Different Paths for Secured Property
The chapter you choose shapes nearly every aspect of your case. Chapter 7 is a liquidation bankruptcy. A trustee reviews your assets, but most filers keep their home and car because the property is either exempt, encumbered by a loan, or both. The case typically lasts three to five months, and you receive a discharge of unsecured debts such as credit cards and medical bills. However, Chapter 7 does not include a built-in mechanism to cure mortgage arrears. If you are behind on payments, you must negotiate a separate agreement with the lender or risk losing the home after the case closes.
Chapter 13 is a reorganization bankruptcy. You propose a repayment plan that lasts three to five years, and that plan can include a cure for missed mortgage payments. This is often the decisive advantage for Pennsylvania homeowners facing foreclosure. The automatic stay remains in place during the plan, and as long as you make the plan payments, the lender cannot foreclose. For car loans, Chapter 13 offers a different benefit: you may be able to reduce the principal balance if the loan is more than 910 days old and you owe more than the car is worth. This process, known as a cramdown, is not available in Chapter 7.
Reaffirmation, Redemption, and Ride-Through
When you file Chapter 7 and want to keep a secured asset, you have three primary options. Reaffirmation is a voluntary agreement with the lender. You sign a new contract that removes the debt from your bankruptcy discharge and continues the original terms, sometimes with a modified interest rate or payment schedule. Reaffirmation reinstates your personal liability, so if you later default, the lender can pursue you for the deficiency balance after repossession or foreclosure. Many attorneys advise caution with reaffirmation unless the terms are clearly favorable and the asset is essential.
Redemption allows you to pay the lender a lump sum equal to the current fair market value of the property. If you owe $12,000 on a car worth $6,000, you can redeem by paying $6,000 and own the car free and clear. The challenge is that redemption requires cash or financing, and not all lenders cooperate smoothly. Ride-through is a third option. In some jurisdictions, you simply keep making payments without reaffirming or redeeming. The lender may tolerate this arrangement, but it is not guaranteed, and some lenders have moved to repossess after discharge when no reaffirmation exists. In Pennsylvania, the safest approach is to confirm your lender's policy in writing before relying on a ride-through.
Curing Mortgage Arrears in Chapter 13
For Pennsylvania homeowners who are behind on their mortgage, Chapter 13 is often the most practical solution. The plan allows you to spread the past-due amount over the life of the repayment plan, typically three to five years, while you resume making regular monthly payments. For example, if you are $15,000 behind on your mortgage, the plan might require an additional $250 per month for five years to cure the arrears. The lender receives those funds through the trustee, and as long as you stay current, the foreclosure is halted permanently.
There is an important distinction between arrears and ongoing payments. The arrears are the missed payments that accumulated before filing. The ongoing payments are the amounts due each month going forward. In Chapter 13, you generally must pay both: the ongoing payment directly to the lender (or through the trustee, depending on local practice) and the arrears through the plan. Failing to make either can lead to dismissal of your case or a motion for relief from the automatic stay, which would allow the lender to resume foreclosure. Pennsylvania courts have seen many cases where homeowners saved their homes by carefully budgeting for both obligations.
If you are facing foreclosure and considering Chapter 13, you do not have to navigate the process alone. LegalCaseReview provides a free case evaluation and connects you with experienced bankruptcy attorneys in Pennsylvania. You can also explore AttorneyLeads for a broader view of how legal lead generation supports access to qualified counsel. The important step is to act before the sheriff's sale, because the automatic stay can only protect you if you file in time.
Credit Reporting and Foreclosure Timing After Filing
Bankruptcy appears on your credit report for seven to ten years, and its impact on your credit score is significant. However, the effect diminishes over time, and many filers see their scores begin to recover within one to two years if they maintain on-time payments on remaining debts. The foreclosure process also has a timeline. In Pennsylvania, a lender must send a notice of intent to foreclose at least 30 days before filing a foreclosure complaint. After the complaint is filed, you have 20 days to respond. If you fail to respond, the lender can seek a default judgment and schedule a sheriff's sale, often within several months.
Filing bankruptcy stops that timeline immediately. The automatic stay is a federal injunction that prevents the lender from proceeding with foreclosure or repossession. If a sheriff's sale is already scheduled, the stay will cancel it unless the lender obtains relief from the bankruptcy court. This is why timing matters: filing even a day before the sale can save your home. However, the stay is temporary. In Chapter 7, it lasts until discharge, after which the lender can resume foreclosure if you are still behind. In Chapter 13, the stay lasts throughout the plan as long as you comply with its terms.
Practical Steps to Protect Your Home and Car in Pennsylvania
If you are considering bankruptcy in Pennsylvania, a clear plan can help you keep your secured property. Start by gathering your mortgage statements, car loan documents, and any foreclosure notices. Then evaluate which chapter fits your income and goals. The means test determines whether you qualify for Chapter 7, but even if you do, Chapter 13 may be better if you need to cure mortgage arrears or cram down a car loan. Here are the key steps to consider:
- Review your exemptions. Pennsylvania's homestead exemption and vehicle exemption set the baseline for what you can protect.
- Calculate your arrears. Know exactly how much you are behind on mortgage and car payments, plus any fees.
- Choose the right chapter. Chapter 7 may work if you are current; Chapter 13 is often better if you are behind.
- Decide on reaffirmation, redemption, or ride-through for your car, and confirm the lender's policy.
- File before the sheriff's sale or repossession to trigger the automatic stay.
After filing, continue making payments on time. In Chapter 13, the trustee will monitor your compliance, and your attorney can help you modify the plan if your circumstances change. If you are unsure where to start, LegalCaseReview offers a free consultation and a directory of Pennsylvania attorneys who handle bankruptcy and secured debt matters.
When to Seek Professional Guidance
The impact of bankruptcy on mortgage and car loans in Pennsylvania is not uniform. It varies by county, by lender, and by the specific facts of your case. A local attorney can review your equity, your income, and your goals, then recommend a strategy that protects your home and vehicle. Many Pennsylvania firms offer free initial consultations, and LegalCaseReview can help you find a qualified lawyer through its patented selection process. Do not wait until the eve of a sheriff's sale. The earlier you explore your options, the more tools you have to keep what matters most.
Bankruptcy is a fresh start, but it is also a process with rules and deadlines. By understanding how secured debts are treated, you can make informed decisions and avoid unnecessary losses. Whether you file Chapter 7 or Chapter 13, the key is to act deliberately and with professional guidance.