How Insurance Adjusters Minimize Personal Injury Settlements
See how insurance adjusters minimize personal injury settlements, from lowball offers to recorded statement traps. Call (833)-279-1850 for a free case review.
By Austin Faherty
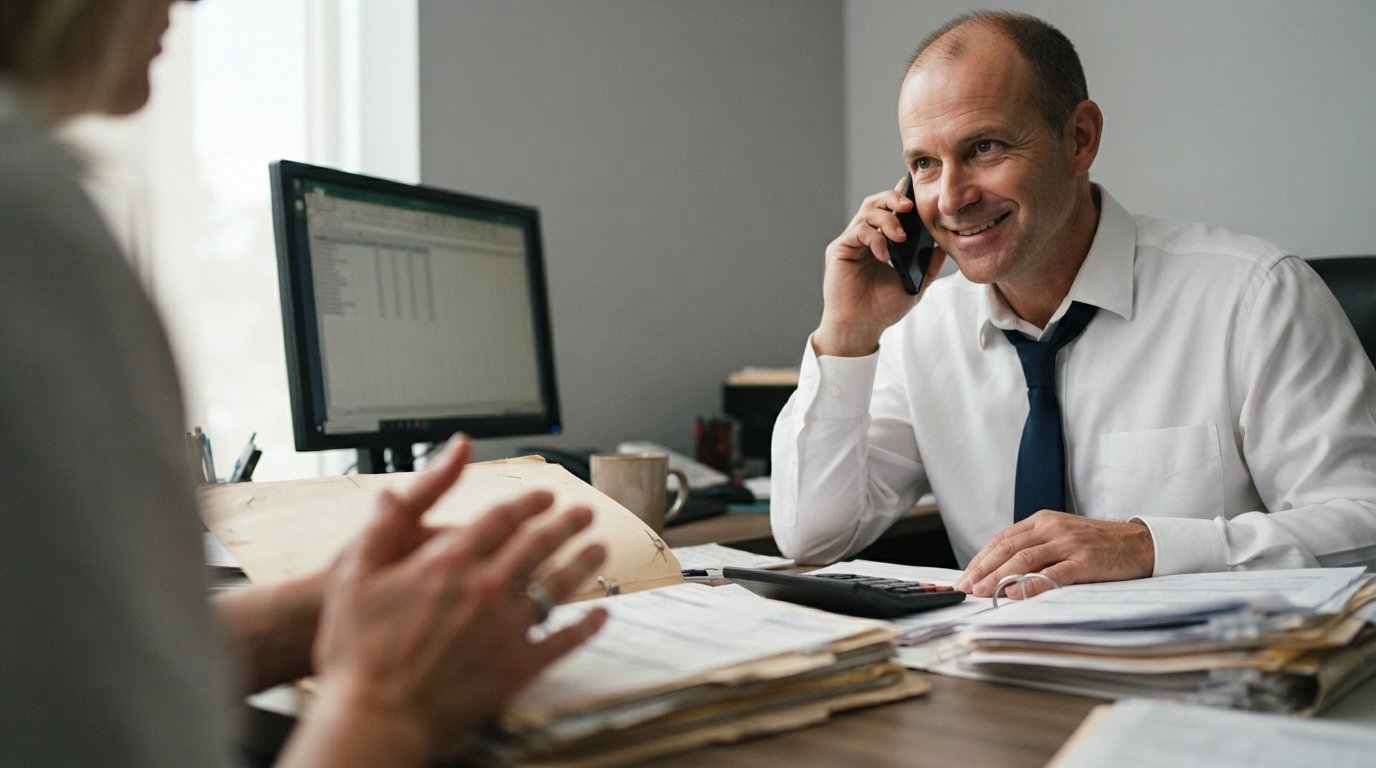
You get the call three days after the crash. The voice on the other end is friendly, almost soothing, and says something like, "We just want to get this resolved quickly so you can move on." That first offer sounds like real money, and the adjuster is happy to explain that it covers your car, your aches, and maybe a little extra for your trouble. What the adjuster will not explain is that the number was calculated to be the lowest amount you might possibly accept, and that every question you answer from here on out will be used to justify keeping it low. Understanding how insurance adjusters minimize personal injury settlements is the first step toward spotting the playbook before it costs you thousands of dollars.
The Adjuster's Job Is Not to Be Fair
Insurance companies are businesses, and claims are expenses. Every dollar an adjuster keeps in the company's reserves is a dollar that counts as a win inside that organization. Adjusters are evaluated on metrics that reward closing files quickly and paying out as little as possible, and many work under settlement authority limits that force them to justify every dollar above a certain threshold. None of this makes the individual adjuster evil. It simply means the person across the phone has a professional incentive that runs in the opposite direction of your recovery.
That is why the same accident can produce wildly different outcomes depending on who is negotiating. A claimant who accepts the first offer without documentation, legal guidance, or a counter, and a claimant who builds a complete file and pushes back, are treated very differently by the same adjuster. The tactics below are the standard tools used to move you toward the low end of that range. Recognizing them is how you get treated like the second claimant. If you want to see how the negotiation changes once a lawyer is involved, our guide on how lawyers deal with insurance adjusters walks through that dynamic in detail.
Low Initial Offers and Quick-Settlement Pressure
The opening offer is a tactic, not a valuation. Adjusters routinely start far below what a claim is worth, sometimes below the documented medical bills, precisely because a meaningful percentage of claimants accept it. The low anchor works because it resets your expectations. If you were imagining $40,000 and the first number you hear is $8,500, your brain starts negotiating against itself before you have looked at a single medical record. The adjuster also knows that an early offer feels generous when your bills are still piling up and you have missed work.
Pressure to move fast is the companion tactic. You will hear that the offer expires, that the supervisor approved it only for this week, that accepting now avoids delays, or that the company's "policy" limits what can be offered later. Almost none of that is real. There is no legal deadline forcing you to accept a quick settlement, and in most states the statute of limitations gives you months or years, not days. An offer that vanishes because you asked a question was not a good offer. The urgency exists to stop you from discovering what your claim is actually worth.
Watch for these pressure points in the first weeks after an accident:
- An offer made before you have finished medical treatment, when the full extent of your injuries is still unknown
- Deadlines described as expiring in days when no legal deadline applies
- Requests to sign a release or waiver before you have reviewed it with anyone
- Offers that conveniently arrive right before a surgery, a specialist visit, or an expected period of lost wages
Once you sign a release, the claim is over. You cannot reopen it if a torn ligament is discovered three months later or if the injury turns out to need surgery. That is exactly why the fast, low offer is timed for the window when you know the least about your own recovery.
Recorded Statements: The Most Expensive Conversation You Will Ever Have
Within days of a crash, the other driver's insurer will call and ask for a recorded statement. The request sounds routine, even helpful, and the adjuster will describe it as a formality needed to "process the claim." It is not a formality. It is a deposition conducted without a lawyer, without preparation, and without any obligation to explain why the questions are being asked.
Adjusters are trained to ask questions whose answers create problems later. Common examples include asking whether you have ever injured that body part before, whether you were taking any medications, whether you told the emergency room doctor you felt fine, and how fast you think you were driving. A harmless-sounding answer about an old back strain becomes the centerpiece of a later argument that your current injury is a pre-existing condition. A comment that you felt "okay" at the scene becomes evidence that you were not really hurt. You are not required to give a recorded statement to the other driver's insurance company, and in most situations you should decline politely and let the evidence do the talking.
The same caution applies to informal conversations. Adjusters keep detailed notes of every call, and casual remarks about your weekend activities, your job, or how you are "feeling much better" can be documented and used against you. Keep communications factual and limited: the date of the accident, the fact that you were injured, and the fact that you are seeking treatment. Everything else can wait until you have representation or a complete file.
Medical Gaps, Prior Injuries, and the Causation Game
The single most effective tool for minimizing a settlement is attacking causation, the link between the accident and your injuries. Adjusters do this in three main ways, and each one has a counter.
The first is the medical gap. If you waited five days to see a doctor, or missed physical therapy for a month, the adjuster will argue that either you were not seriously hurt or that something else happened during the gap. The counter is documentation and explanation. Gaps happen for real reasons: fear of cost, lack of insurance, hoping the pain would fade, or simply not knowing where to go. A treating physician who understands the timeline can address it in the records, and a personal injury attorney can present the gap in context rather than letting the adjuster define it.
The second is prior injury history. Adjusters pull your medical records and hunt for any earlier complaint involving the same body part, then argue the current symptoms are a flare-up of an old problem. The counter is medical evidence that distinguishes the new injury from the old one, which is why a gap in treatment before the accident can actually help you. If you had a bad back in 2022 but were symptom-free and working normally in the year before the crash, the records can show that.
The third is the degenerative finding. Almost every adult over 40 has some arthritis or disc degeneration on an MRI, and adjusters treat those findings as a discount coupon. The argument is that the imaging shows a pre-existing condition, so the accident cannot be responsible. The counter is the difference between a condition that shows up on a scan and a condition that causes pain and disability. A physician can explain that the accident aggravated or accelerated a dormant condition, which is a legitimate injury in the eyes of the law.
This is also why treatment consistency matters so much. A claimant who follows the treatment plan, keeps every appointment, and documents symptoms in a journal is far harder to minimize than one whose records show gaps and contradictions. The adjuster is not evaluating whether you are honest. The adjuster is evaluating whether the file gives them room to argue, and a well-documented file removes that room.
How Adjusters Value (and Devalue) Your Claim
Adjusters use software and formulas to generate a claims range, but the inputs are controlled by the file you build. The calculation typically weighs medical expenses, lost wages, future care, pain and suffering, and liability strength. Each input is an opportunity to reduce the number. Medical bills get scrutinized for reasonableness, and treatment from certain providers is discounted or flagged as "built up." Lost wages get challenged without clear employer documentation. Pain and suffering, the most subjective component, gets compressed using formulas that vary by company and adjuster.
Liability is another lever. Even in a clear rear-end collision, the adjuster may raise comparative fault, arguing that you contributed to the crash by braking suddenly or by not wearing a seatbelt. In many states, any assigned percentage of fault reduces your recovery proportionally, so a 20 percent fault argument quietly removes a fifth of your settlement. Adjusters raise these arguments not because they are strong but because they create doubt, and doubt is leverage.
Here is what a complete, negotiation-ready file looks like, and why each piece matters:
- All medical records and bills, from the emergency room through the final specialist visit, organized by provider and date, so the adjuster cannot claim treatment is undocumented.
- Wage loss proof, including employer letters, pay stubs, and tax returns, which converts lost income from a claim into a number the adjuster must accept.
- A physician's narrative connecting the accident to the injuries and describing future care, which directly answers the causation attack.
- Accident and property damage evidence, including photos, the police report, and repair estimates, which supports liability and injury severity.
- A demand package with a clear damages calculation, which anchors the negotiation at your number instead of the adjuster's.
Notice what this file does: it removes the ambiguity the adjuster needs to minimize the offer. When the records, the wages, the causation opinion, and the liability evidence all point one direction, the adjuster's authority to lowball shrinks. That is why experienced negotiators spend most of their effort on the file before they ever discuss a number.
Recognizing the Tactics and Building Leverage
Beyond the low offer and the recorded statement, adjusters use a set of softer tactics designed to wear claimants down. They may delay responses for weeks, then present a "final" offer with a short deadline. They may express sympathy while explaining that the company simply cannot pay more. They may ask you to provide records yourself, hoping you will not bother. They may split the difference repeatedly, each time moving the number slightly closer to yours while never reaching fair value. Each tactic is designed to make settlement feel like relief rather than a result.
The most reliable counter is leverage, and leverage comes from three places: a complete file, a credible willingness to litigate, and professional representation. Insurers track which claims are represented and which are not, and the evaluation changes accordingly. A claimant who has documented the case, declined the recorded statement, avoided the quick offer, and consulted a professional is a very different risk profile from one who has done none of those things. If you are still deciding how to proceed, a free case evaluation can tell you what your claim is realistically worth before you accept anything.
For readers who want to understand their options and connect with qualified attorneys, platforms such as LawyerOffer provide educational resources and attorney referral services for personal injury and insurance claims. LegalCaseReview also offers free, no-obligation case evaluations that can help you compare your situation against how similar claims are typically valued. The point is not to complicate a simple claim; it is to make sure a simple claim is not settled as if it were worth nothing.
What to Do Before You Accept Any Offer
Before you sign anything, slow down and run through a short checklist. Confirm that your medical treatment is complete or that the offer accounts for future care. Confirm that every lost wage is documented. Confirm that the offer includes pain and suffering, not just bills. Confirm that no lien or health insurance reimbursement will eat the settlement after you receive it. And confirm that you understand what you are giving up when you sign the release.
If any of those answers is unclear, the offer is not ready to accept. Adjusters minimize settlements by exploiting uncertainty: uncertainty about your injuries, your rights, and your alternatives. The cure is information, documentation, and patience. You do not have to out-argue an adjuster on the phone. You simply have to refuse to settle until the file tells the full story, and that alone changes the math in your favor.