How Insurance Companies Investigate a Personal Injury Claim
Insurers dig deep into your claim. Call (833)-279-1850 to understand how insurance companies investigate a personal injury claim and protect your recovery.
By Dina Morello
You filed a personal injury claim after an accident, and now the insurer is asking questions, requesting records, and possibly even watching you. Understanding what happens behind the scenes can feel like trying to read a sealed book. But the investigation process is not magic, and it is not random. Insurance companies follow a fairly predictable playbook designed to gather facts, test credibility, and control payout risk. Knowing how that playbook works gives you a serious advantage when you are the one filing the claim.
This article breaks down how insurance companies investigate a personal injury claim from the first notice of loss to the final file review. You will see the specific steps adjusters take, how recorded statements and medical records are used, what accident reconstruction and independent medical exams actually mean, and how investigation differs from negotiation. You will also learn practical ways to protect your case while the insurer digs into the details. If you are considering professional help, resources like LawyerOffer can connect you with attorneys who understand this process inside and out.
The Investigation Begins: First Notice of Loss and the Adjuster's Role
The investigation clock starts the moment the insurer receives notice of your claim. This first report, often called the first notice of loss, sets the tone for everything that follows. A claims adjuster is assigned, and that person becomes the primary investigator, evidence collector, and decision-maker on whether to accept, deny, or dispute the claim. The adjuster's job is not to be fair in a moral sense; it is to resolve the claim at the lowest defensible cost.
During those early days, the adjuster gathers basic facts: who was involved, when and where the incident occurred, what injuries were reported, and whether any police or incident reports exist. They may pull the police report, check for prior claims involving the same parties, and review the policy to confirm coverage limits and exclusions. This is also when the adjuster starts building a theory of the case, even if that theory is rough and preliminary.
One of the first things the adjuster wants is a recorded statement. This is not a casual conversation. It is a structured interview, usually conducted by phone, that is recorded and later transcribed. The adjuster is listening for inconsistencies, admissions, and details that can be used to reduce the value of the claim. They may ask about your medical history, prior accidents, and activities before and after the incident. The purpose is to lock you into a version of events and to identify anything that contradicts the medical records or the physical evidence.
You are generally not required to give a recorded statement to the other driver's insurer, and doing so without preparation can harm your case. If you choose to give one, keep your answers factual, consistent, and limited to what you personally observed. Avoid guessing, speculating, or offering opinions about fault or injury severity. For a deeper look at how these early statements influence the final number, see our guide on how insurance companies calculate payouts for injury claims.
Gathering Evidence: Records, Reports, and Reconstruction
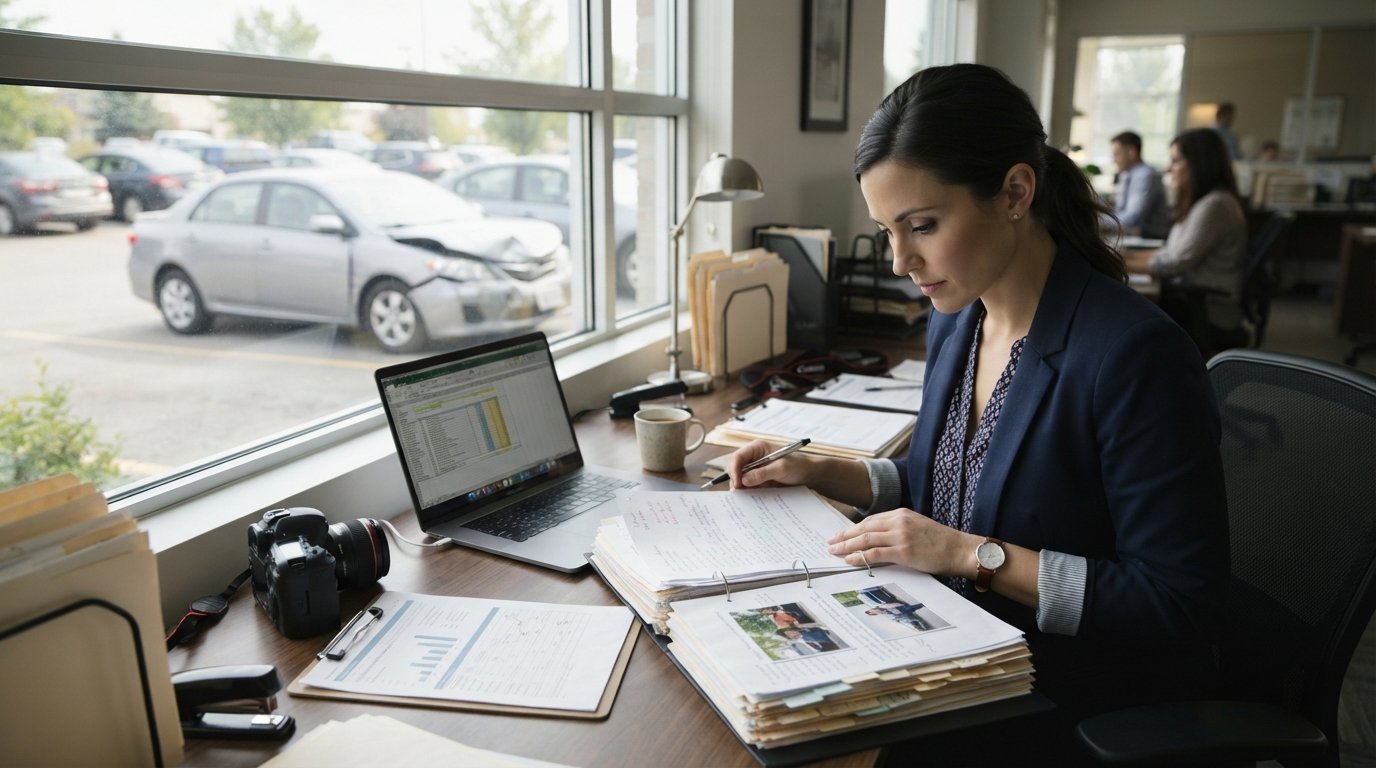
After the initial statements, the adjuster shifts into evidence-gathering mode. This phase is where the paper trail and the physical facts come together. The insurer will request medical records, billing statements, and sometimes employment records to verify lost wages. They may also obtain the police report, witness statements, and photographs or video from the scene. In vehicle accident cases, the adjuster may review the property damage estimates and repair invoices to understand the force of impact and correlate it with the claimed injuries.
Accident reconstruction is a tool insurers use when liability or injury causation is disputed. An insurance company may hire an accident reconstructionist to analyze skid marks, vehicle damage patterns, road conditions, and witness accounts to estimate speeds, angles, and impact forces. The goal is often to show that the impact was low-speed or that the claimant's version of events is physically impossible. In slip and fall or premises liability cases, reconstruction may involve reviewing surveillance footage, maintenance logs, and inspection records to determine whether the property owner had notice of a hazard.
Surveillance is another investigative technique that surprises many claimants. Insurers can and do hire investigators to conduct surveillance, especially when a claim involves soft tissue injuries, subjective complaints like pain, or a significant wage loss claim. They may record video of you doing yard work, carrying groceries, or engaging in recreational activities. The footage is then compared against your medical records and your statements about your limitations. If the video shows you doing something your doctor said you could not do, the insurer will use it to challenge your credibility and reduce or deny the claim.
Here is a simple summary of the evidence an adjuster commonly collects during a personal injury investigation:
- Recorded statements from the claimant, witnesses, and sometimes the insured driver
- Police or incident reports and any citations issued
- Medical records, billing statements, and diagnostic imaging reports
- Employment and wage records to support lost income claims
- Photographs, video surveillance, and accident reconstruction reports
Each piece of evidence is evaluated not only for what it proves but also for what it undermines. The adjuster is looking for gaps, contradictions, and opportunities to argue that the injury was pre-existing, exaggerated, or unrelated to the accident.
Medical Record Review and the Independent Medical Exam
Medical evidence is the backbone of most personal injury claims, and insurers review it with a skeptical eye. The adjuster will request your medical records from the treating providers, often starting with the emergency room or urgent care visit and continuing through follow-up care. They are looking at the mechanism of injury, the diagnosis, the treatment plan, the duration of care, and whether there are any pre-existing conditions that could explain your symptoms.
One of the most important steps in the investigation is the independent medical examination, often called an IME. Despite the name, an IME is not truly independent. The doctor is selected and paid by the insurance company. The examination is typically brief, and the resulting report often concludes that the claimant's injuries are not as severe as claimed, that they have resolved, or that they are unrelated to the accident. The adjuster uses the IME report to justify a lower settlement offer or to support a denial.
You are usually required to attend an IME if you are pursuing a claim, but you can prepare for it. Bring your medical records, be honest about your symptoms, and do not exaggerate or minimize. If the IME doctor asks you to perform movements that cause pain, say so clearly. The goal is to create a record that is consistent with your treating physicians' findings. If the IME report conflicts with your treatment records, your attorney can challenge it, but the insurer will still use it as leverage in negotiation.
Insurers also use medical bill audits and reviews by nurse consultants to scrutinize the reasonableness and necessity of treatment. They may argue that certain procedures were unnecessary, that the charges are above customary rates, or that the treatment was prolonged beyond what the injury required. This is why documenting every visit, diagnosis, and prescription is critical. The more consistent and well-documented your medical care, the harder it is for the insurer to discount it.
How Claimants Can Protect Their Case During an Investigation
You do not have to be a passive subject of the insurer's investigation. There are concrete steps you can take to protect your claim and level the playing field. The first is to be careful with communication. Do not give a recorded statement to the other party's insurer without legal advice, and do not post about your accident, injuries, or activities on social media. Insurers routinely review public profiles for evidence that contradicts your claim. Even a check-in at a restaurant or a photo from a vacation can be taken out of context and used against you.
The second step is to document everything. Keep a journal of your pain, treatment, and limitations. Save receipts, bills, and correspondence. Take photos of your injuries, the accident scene, and any property damage. If you return to work on light duty or have restrictions, get them in writing from your doctor. This contemporaneous evidence is powerful because it is created close to the events and is harder to challenge than later recollections.
The third step is to consider professional representation early. An experienced personal injury attorney can handle communications with the adjuster, prepare you for a recorded statement or IME, and gather evidence that supports your claim. Attorneys also understand the insurer's investigation tactics and can push back when the insurer overreaches. If you are unsure where to start, a service like LegalCaseReview can provide a free case evaluation and connect you with vetted attorneys who focus on personal injury claims.
Finally, be patient but proactive. Investigations take time, and the insurer may request multiple extensions or additional records. Stay responsive to reasonable requests, but do not let the insurer dictate the pace. Keep a calendar of deadlines and follow up on requests in writing. If the insurer is delaying unreasonably, that delay itself can become part of your negotiation strategy.
Investigation vs. Negotiation: Understanding the Difference
Many claimants confuse the investigation with the negotiation. They are related but distinct phases. The investigation is about fact-finding: what happened, what injuries resulted, what treatment was received, and what evidence exists. The negotiation is about value: how much the claim is worth and what the insurer is willing to pay. The investigation informs the negotiation, but it does not determine the outcome by itself.
During the investigation, the adjuster is building a file that will support a reserve, which is the amount the insurer sets aside to pay the claim. The reserve is not disclosed to you, but it influences the adjuster's settlement authority. If the investigation reveals strong evidence of liability and significant damages, the reserve will be higher, and the adjuster will have more room to negotiate. If the investigation reveals weaknesses, the reserve will be lower, and the adjuster will push for a lower settlement or a denial.
Negotiation typically begins after the investigation is substantially complete, or at least after the insurer has enough information to make an initial offer. That offer is usually low, and it is expected that you or your attorney will counter. The negotiation process involves demand letters, counteroffers, and sometimes mediation. The investigation does not stop entirely during negotiation; the insurer may continue to gather evidence, especially if new information emerges. But the focus shifts from fact-finding to bargaining.
Understanding this distinction helps you avoid a common mistake: treating the initial offer as a final verdict on your claim. The investigation may have produced a file that supports a higher value, but the adjuster's first offer is just a starting point. With the right evidence and advocacy, you can move the number significantly.
What the Insurer Is Really Looking For
At the heart of every investigation is a simple question: what is the risk of paying this claim? The insurer is assessing liability risk, damages risk, and fraud risk. Liability risk is about who caused the accident and whether the insured is legally responsible. Damages risk is about the extent of the injuries and the reasonableness of the medical bills and other losses. Fraud risk is about whether the claim is legitimate or exaggerated.
Insurers use various tools to assess these risks, including claims databases, prior claim history, and social media monitoring. They may also use scoring models that predict the likelihood of fraud or the expected payout based on the type of accident and injury. These tools are not perfect, but they influence how the adjuster handles your claim. If your claim is flagged as high-risk, expect more scrutiny, more requests for documentation, and more resistance during negotiation.
The best way to counter this is to be organized, consistent, and transparent. Provide the records the insurer reasonably requests, but do not volunteer information that is not asked for. Keep your story straight, and make sure your medical records and your statements align. If there are gaps in your treatment, explain them. If you had a pre-existing condition, disclose it and explain how the accident aggravated it. Honesty and consistency are your strongest allies.
When to Bring in Legal Help
Not every claim requires an attorney, but many do. If your injuries are serious, if liability is disputed, if the insurer is requesting a recorded statement or an IME, or if you feel overwhelmed by the process, it is worth speaking with a personal injury lawyer. Attorneys handle these investigations every day and know how to respond to insurer tactics. They can also help you avoid mistakes that could permanently damage your claim.
LegalCaseReview offers a free, no-obligation case evaluation and a patented attorney selection process that identifies top-rated lawyers in your area. You can get quick quotes and compare your options without pressure. If you are not ready to hire an attorney, you can still use the site's educational resources to understand your rights and the investigation process. The goal is to make informed decisions, not to rush into anything.
The investigation of a personal injury claim is a structured process with predictable stages. By understanding what the insurer is doing and why, you can protect your interests and put yourself in a better position to negotiate a fair settlement. Whether you handle the claim yourself or work with an attorney, knowledge is your best defense against an insurer that is trained to minimize payouts.