Pennsylvania Diminished Value Claim: Car Accident Property Damage
Recover full vehicle value after a crash with a property damage claim after car accident Pennsylvania diminished value strategy. Call (833)-279-1850 for help.
By Lenora West
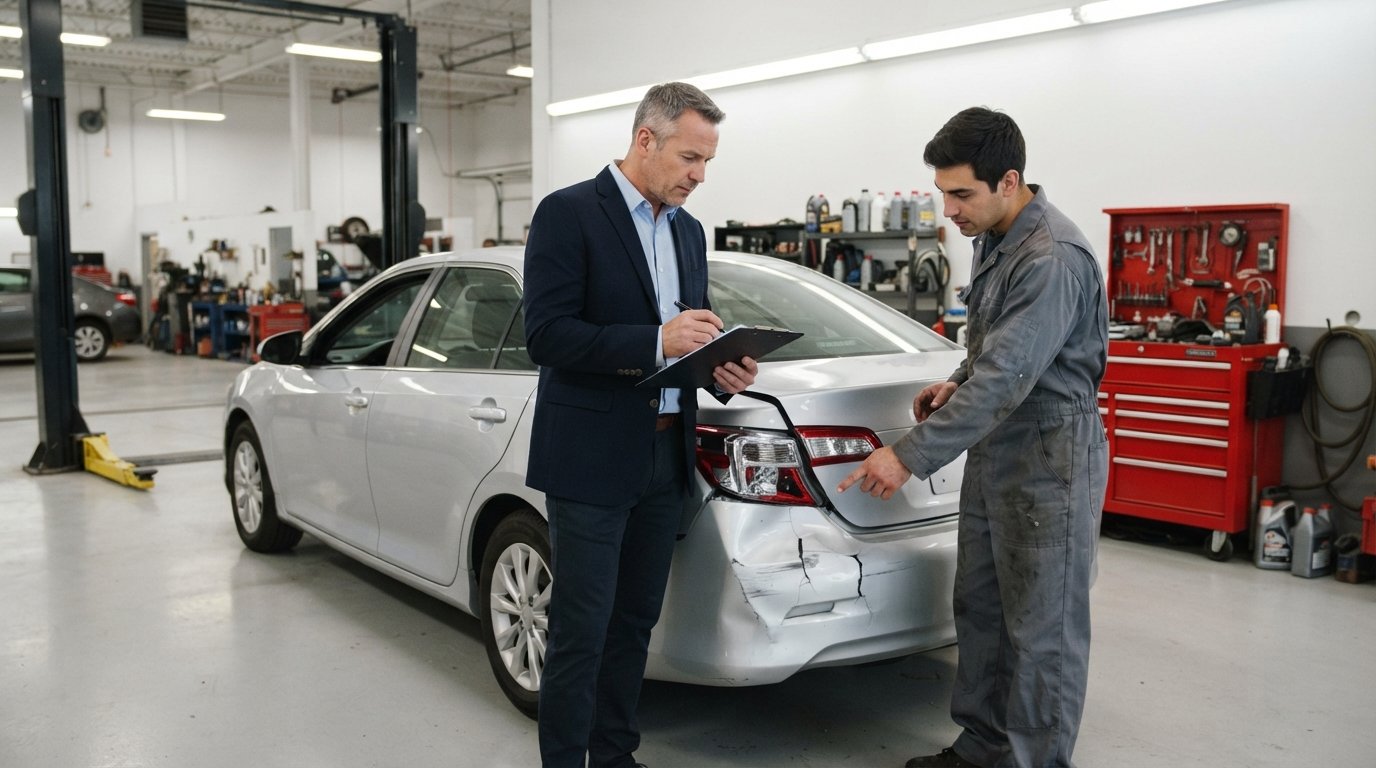
A car accident in Pennsylvania can leave you with more than visible damage. Even after your vehicle is repaired to factory specifications, its resale value may drop simply because it now has a documented accident history. If you are pursuing a property damage claim after a car accident in Pennsylvania, diminished value is a critical concept that could recover thousands of dollars beyond the repair bill. Yet many drivers never ask for it, and insurers rarely volunteer that it exists.
This guide explains how Pennsylvania law treats property damage claims, how diminished value works in practice, how to prove your loss when the other driver was at fault, and why the paperwork you sign can quietly extinguish your rights. The goal is practical clarity: what to ask for, what to document, and when to bring in professional help. For readers navigating a broader or more serious claim, resources such as this guide on wrongful death claims after fatal crashes illustrate how property and injury matters can intersect, though the focus here stays on the vehicle itself.
Understanding Property Damage Claims in Pennsylvania After a Crash
Pennsylvania is a choice no-fault state for injury claims, but property damage is handled differently. When another driver causes the crash, you generally have the right to pursue the at-fault driver's liability insurer for the cost of repairing or replacing your vehicle. You may also route the claim through your own collision coverage, but that typically involves a deductible and may affect your premiums. The strategic question is which path recovers the most money with the least friction.
It helps to separate the property damage claim from any bodily injury claim. They are distinct legal claims with separate negotiations, separate adjusters, and sometimes separate deadlines. Bundling them can create confusion, and a low property damage offer can anchor the entire conversation. Treat the vehicle claim as its own negotiation with its own evidence file, even if the same insurer handles both.
A property damage claim in Pennsylvania can include several categories of loss. Knowing them upfront prevents the adjuster from framing the conversation around repair costs alone.
- Repair costs, including parts and labor at a shop of your choosing
- Diminished value, the loss in resale worth caused by the accident history
- Loss of use, such as rental car costs during repairs
- Towing and storage fees, plus post-repair diagnostics
- Total loss compensation if repairs exceed the vehicle's value
Each category requires its own proof. Repair invoices are straightforward, but diminished value and loss of use demand documentation and, often, negotiation. Adjusters are trained to settle quickly and cheaply, so the burden falls on you to present a complete picture of what the crash actually cost you.
What Diminished Value Means and Why Insurers Resist It
Diminished value is the difference between what your vehicle was worth immediately before the accident and what it is worth after being repaired. A clean vehicle history report commands a higher price in the used market. Once a crash appears on that report, buyers discount the car, and that discount is a real financial loss to you, even though the car drives perfectly.
Pennsylvania recognizes diminished value as a recoverable element of property damage when the other driver is at fault. In practice, however, insurers often deny or lowball these claims. Common tactics include arguing that diminished value is not owed under the policy language, that the vehicle was repaired so no loss exists, or that the concept only applies to rare or exotic cars. None of these arguments is a legal absolute, and each can be challenged with the right evidence.
There are three generally recognized types of diminished value, and knowing them helps you frame your demand. Immediate diminished value is the loss measured at the moment of the accident before repairs. Repair-related diminished value reflects concerns that repairs were incomplete or lower quality. Inherent diminished value is the stigma of the accident history itself, which persists even after perfect repairs. Inherent diminished value is the most commonly claimed type and the one most often disputed.
Timing matters as well. Diminished value is easiest to prove while the vehicle is still relatively new or high-value, and before you sell it. If you wait years, the loss becomes harder to quantify and the insurer will argue that normal depreciation has swallowed it. Raising the issue early, in writing, preserves your position.
How to Prove Diminished Value in a Pennsylvania Claim
Proof is where most diminished value claims succeed or fail. A general assertion that your car is worth less will not move an adjuster. You need a documented, methodical estimate that connects the accident history to a specific dollar figure. The most persuasive approach is a written diminished value appraisal prepared by an independent appraiser who specializes in this work.
That appraisal typically uses a market comparison or formula-based method, such as the 17c formula that many insurers reference, though independent appraisers often argue the formula understates real market loss. The report should identify your vehicle's pre-accident value, the nature and severity of damage, the quality of repairs, and comparable market data showing discounted prices for vehicles with accident history.
A strong evidence file includes more than the appraisal. Gather the following before you open negotiations:
- A copy of the police crash report identifying the other driver's fault
- Pre-accident photos and maintenance records showing condition
- Complete repair estimates and final invoices, including supplements
- Car history reports showing the accident entry after repairs
- An independent diminished value appraisal with supporting market data
Once assembled, present the package in writing with a specific demand and a reasonable deadline for response. Keep the tone factual. Adjusters respond better to organized documentation than to frustration, and a clear paper trail becomes valuable if the dispute later moves to appraisal, mediation, or court. If the insurer refuses to engage, a demand letter from an attorney often changes the calculation.
Total Loss Valuation Disputes in Pennsylvania
When repairs cost more than the vehicle is worth, the claim becomes a total loss. Pennsylvania uses a total loss threshold tied to the cost of repairs relative to the vehicle's actual cash value, and insurers must use approved valuation methods. The dispute usually centers on that actual cash value figure, which insurers derive from third-party valuation vendors using comparable vehicles, mileage adjustments, and condition ratings.
Those valuations are frequently beatable. Common errors include using comparables from the wrong region, ignoring optional equipment and packages, misgrading condition, and applying aggressive mileage deductions. If your car was well maintained with low miles and desirable options, the first offer may be thousands below fair market value.
You have the right to challenge the valuation with your own evidence. Collect dealer listings for comparable vehicles within a reasonable radius, gather receipts for recent major maintenance such as tires or a transmission, and document any factory options. Some policies include an appraisal clause that allows each side to hire an appraiser and, if they disagree, a neutral umpire decides. That clause can be a powerful tool when negotiations stall.
Total loss claims also raise practical questions about salvage, loan balances, and gap coverage. If you owe more than the vehicle is worth, the settlement may not clear the loan, and separate gap insurance may apply. Review the settlement breakdown carefully so you understand what is being paid, to whom, and whether any fees are deducted.
Why a Liability Release Can End Your Property Claim
One of the most costly mistakes drivers make is signing a release without reading it closely. Insurers often present a release that resolves the property damage claim, and sometimes the bodily injury claim as well, in exchange for a payment. Once signed, that release typically ends your ability to seek more money for the same incident, including diminished value you had not yet discovered.
The danger is timing. A release may arrive quickly after repairs, before you have an appraisal or before the accident appears on a vehicle history report. Signing at that point can permanently waive the diminished value claim. The same risk applies to cashing a settlement check that contains release language, since endorsement can be treated as acceptance of the terms.
Protect yourself by taking these steps before signing anything:
- Read the entire release and identify exactly which claims it covers.
- Confirm whether diminished value is mentioned, included, or waived.
- Do not sign until repairs are complete and you have an appraisal in hand.
- Ask for the release in writing and take time to review it, even if pressured.
- Consult an attorney if the language is broad or the stakes are significant.
A properly drafted release can be limited to specific items, such as repair costs, while preserving other claims. If the insurer insists on a full release before you have evaluated diminished value, that is a signal to slow down and get advice. Platforms that connect consumers with attorneys, such as LawyerOffer, exist precisely to help people understand documents like these before signing away rights.
Steps to Pursue a Diminished Value Claim in Pennsylvania
With the concepts clear, the process becomes manageable. The sequence below reflects how a well-organized claim typically unfolds, from the scene of the crash to a negotiated resolution.
- Document the accident scene, damage, and the other driver's information.
- Notify the at-fault insurer in writing that you intend to claim property damage, including diminished value.
- Complete repairs at a qualified shop and keep every estimate, supplement, and invoice.
- Obtain an independent diminished value appraisal after repairs are finished.
- Submit a written demand package with supporting evidence and a response deadline.
- Negotiate, and escalate to appraisal, mediation, or legal action if the offer remains unfair.
Throughout this process, keep a written log of every call, email, and offer. Adjusters change, memories fade, and a contemporaneous record strengthens your position. If the insurer delays or denies without a reasoned basis, that pattern itself becomes useful evidence in a formal dispute.
Pennsylvania's statute of limitations for property damage claims is generally two years from the date of the accident, but do not treat that as permission to wait. Evidence deteriorates, appraisers become harder to schedule, and insurers grow less cooperative over time. Moving promptly also preserves your options if the claim needs to be combined with an injury matter later.
When to Bring in Professional Help
Many diminished value claims can be handled directly with a solid appraisal and persistent follow-up. Professional help becomes worthwhile when the numbers are large, the insurer is stonewalling, a release is on the table, or the vehicle is a high-value model where the loss could reach five figures. An attorney can also assess whether the property claim should be coordinated with a bodily injury claim, since inconsistent statements across the two files can undermine both.
LegalCaseReview provides educational resources and a free case evaluation process to help drivers understand their options before committing to representation. A short consultation can clarify whether your diminished value claim is worth pursuing, what evidence you still need, and how to respond to a low offer. That guidance is especially valuable in Pennsylvania, where property damage rules, total loss thresholds, and release language all interact in ways that are easy to misread without experience.
The bottom line: a repaired car is not made whole if its value has dropped. Treat the property damage claim as a separate negotiation, document everything, get an independent appraisal, and never sign a release until you understand exactly what it covers. Drivers who approach the process methodically routinely recover more than those who accept the first check and move on.