What Is a Recorded Statement in a Car Accident Claim?
Understand what a recorded statement in a car accident claim involves and how to protect your rights. Call (833)-279-1850 for a free case review.
By Declan Ward
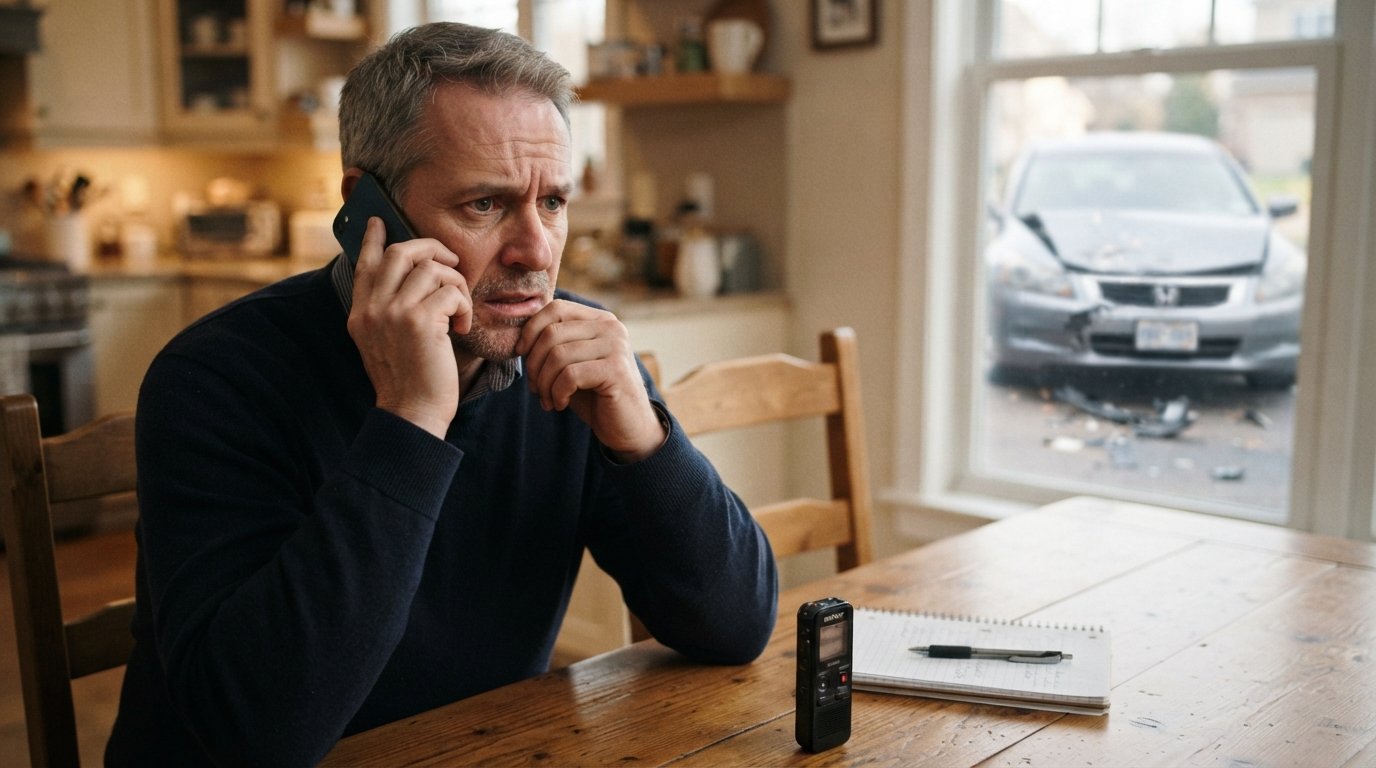
Your phone rings a few days after a car accident. The voice on the other end identifies as an adjuster from the other driver's insurance company. After a few pleasantries, they ask if you have a few minutes to give a recorded statement about the crash. It sounds routine, almost helpful. But that single conversation can shape the entire financial outcome of your injury claim, often before you have spoken to a lawyer or even finished treating your injuries. Understanding what a recorded statement is in a car accident claim, why insurers want one, and what you are legally required to do can protect you from saying something that later undermines your recovery.
A recorded statement is a formal, audio-recorded conversation between an insurance adjuster and a person involved in an accident. The adjuster asks questions about the crash, your injuries, your medical history, and your background, and the entire exchange is captured on tape or in a digital recording. That recording becomes part of the claim file and can be used later during settlement negotiations or even at trial. For the insurer, the recording is evidence. For you, it is a permanent record of your words that may be replayed, quoted, and scrutinized long after your memory of the event has faded.
Why Insurance Adjusters Ask for Recorded Statements
Insurance companies are businesses, and their goal is to resolve claims for as little money as possible. A recorded statement serves several strategic purposes for the adjuster. First, it locks you into a version of events early, often before you have had a chance to review police reports, medical records, or witness accounts. If your memory changes later, even for innocent reasons, the insurer can point to the recording as proof of inconsistency. Second, the adjuster is listening for admissions of fault, exaggerations, or gaps in your story that can be used to reduce or deny your claim.
Third, the recording can be used to probe your medical history. Adjusters often ask broad questions about prior injuries, previous accidents, and existing health conditions. A careless answer, such as confirming that you had back pain before the crash, can give the insurer grounds to argue that your current symptoms are unrelated to the accident. Fourth, the statement establishes a timeline. If you say you were not injured at the scene but later seek treatment for neck pain, the insurer may argue that your injuries are exaggerated or developed from something else.
Finally, the recorded statement can be used to assess your credibility and demeanor. Adjusters are trained to notice hesitation, frustration, and inconsistencies. A claimant who sounds angry or rehearsed may be treated differently than one who is calm and factual. None of this means the adjuster is acting in bad faith; it simply means the process is designed to gather information that benefits the insurer's position.
The Risks of Giving a Statement Without Preparation
The biggest risk of giving a recorded statement is that you do not know what the adjuster is really asking. Questions that seem simple can be traps for the unwary. For example, an adjuster might ask, "How fast were you going?" If you estimate a speed that is slightly higher than the posted limit, the insurer may argue that you were speeding and therefore partially at fault. Or they might ask, "Have you ever had neck pain before?" If you mention a minor ache from years ago, the insurer may claim your current injury is pre-existing.
Another risk is that you may not yet know the full extent of your injuries. Soft tissue injuries, concussions, and internal damage often take days or weeks to manifest. If you give a statement on day three and say you feel fine, the insurer will use that statement against you when you later seek treatment for chronic pain. Similarly, you may not have reviewed your own medical records or the police report, so you may misstate important details about the accident.
There is also the risk of unintentional admissions. You might say something like, "I didn't see the other car until it was too late," which the insurer could interpret as an admission that you were not paying attention. Or you might apologize, saying, "I'm sorry, I should have been more careful," which can be treated as an admission of fault even if you were not legally responsible. In the stress of the moment, it is easy to say things you do not mean.
Finally, a recorded statement can create a permanent record that follows you throughout the claim. Even if you later hire an attorney and clarify your statements, the original recording remains. The insurer can use it to impeach your credibility, and opposing counsel can play it for a jury if the case goes to trial. Once something is recorded, it cannot be taken back.
Are You Legally Required to Give a Recorded Statement?
In most car accident cases, you are not legally required to give a recorded statement to the other driver's insurance company. The other insurer has no legal authority to compel you to speak with them, and you are free to decline or to end the conversation at any time. Your obligation to cooperate typically arises only with your own insurance company, and even then, the requirement depends on the terms of your policy.
If you file a claim with your own insurer, such as a personal injury protection (PIP) claim or a collision claim, your policy likely includes a cooperation clause. That clause may require you to provide a statement, but it does not necessarily require a recorded statement. Many policies require you to submit to an examination under oath (EUO) in certain circumstances, but a routine recorded statement is often a request, not a demand. You should review your policy language carefully or consult an attorney if you are unsure.
It is important to distinguish between a recorded statement and a sworn statement or deposition. A deposition is part of the litigation process and is conducted under oath with a court reporter present. If your case is in litigation, you will be required to participate in discovery, including a deposition. But a recorded statement taken by an adjuster before a lawsuit is filed is a voluntary process. You can say no.
That said, refusing to give any statement at all can sometimes harm your claim. The adjuster may interpret your refusal as evidence that you have something to hide, and the insurer may delay or deny your claim. The better approach is often to decline the recorded statement politely while offering to provide a brief, unrecorded statement or to answer questions in writing. This preserves your cooperation while protecting your words.
How to Handle a Request for a Recorded Statement
If an adjuster asks for a recorded statement, you do not have to decide on the spot. You can politely say, "I would like to consult with an attorney before making any recorded statements. Please send me your request in writing." This gives you time to assess your options and to speak with a lawyer if you choose to do so. In the meantime, you can provide basic information such as your name, address, and the date of the accident, but you should avoid discussing fault, injuries, or medical history.
If you decide to give a recorded statement, preparation is essential. Before the call, review the police report, your medical records, and any photos or witness statements you have. Write down a timeline of events and key facts so you can refer to them during the call. Do not memorize a script, but do have notes in front of you. Ask the adjuster to confirm that the call is being recorded and to state their name and company. You can also ask for a copy of the recording afterward.
During the statement, follow these guidelines:
- Answer only the question asked. Do not volunteer extra information or speculate about what might have happened.
- If you do not know or do not remember, say so. "I don't recall" is a complete and acceptable answer.
- Do not guess about speed, distance, or time. If you are unsure, say you are unsure.
- Avoid words like "always," "never," and "obviously." They can be used to challenge your credibility.
- Do not apologize or admit fault. Even a polite "I'm sorry" can be misconstrued.
- Take your time. Pause before answering, and ask the adjuster to repeat or clarify any question you do not understand.
- If you need a break, ask for one. You are not obligated to continue if you feel overwhelmed.
After the statement, you can request a copy of the recording and a transcript. Review them carefully. If you notice errors, you can send a written correction to the adjuster. Keep a record of all communications, including dates, times, and the names of the people you spoke with.
When to Involve an Attorney Before Speaking
There is no universal rule for when to hire a car accident attorney, but there are clear situations where speaking to an insurer without legal guidance is risky. If you have suffered serious injuries, if the accident involved multiple vehicles or a commercial truck, if liability is disputed, or if the insurer has already hinted that you may share fault, you should consult an attorney before giving any recorded statement.
An attorney can handle the adjuster for you, which means you do not have to speak to the insurer at all. Your lawyer can provide the necessary information, negotiate the claim, and protect you from making statements that could harm your case. Many personal injury attorneys offer free consultations, so you can get advice without any upfront cost. If you are unsure whether you need a lawyer, a brief consultation can help you decide.
In addition, if you have unpaid medical bills or are worried about how your settlement will be distributed, it helps to understand the bigger picture. For example, a lien on a car accident settlement can reduce your net recovery, and a recorded statement that downplays your injuries can make it harder to resolve those liens. Speaking with an attorney early can help you avoid these complications.
For attorneys and law firms looking to connect with individuals who need legal help, platforms like AttorneyLeads provide pre-screened leads and marketing support. But for accident victims, the priority is protecting your rights. If you are unsure about a recorded statement, consider reaching out to a trusted legal resource. LegalCaseReview offers free case evaluations and can connect you with experienced attorneys who can advise you on how to handle insurer requests. You can learn more about what is a lien on a car accident settlement and other claim-related issues through their educational resources.
What to Do If You Already Gave a Statement
If you have already given a recorded statement and are worried about what you said, do not panic. You cannot undo the recording, but you can take steps to mitigate any damage. First, write down everything you remember about the statement, including the questions asked and your answers. Second, if you made a mistake or left something out, you can send a written correction to the adjuster. Third, consult an attorney as soon as possible. A lawyer can review the recording and advise you on how to proceed.
In some cases, an attorney can argue that your statement was taken before you had a chance to review the evidence or consult with counsel, and they can provide additional context. But the best defense is prevention: if you have not yet given a statement, prepare carefully or decline until you have legal advice.
Remember that the insurance adjuster is not on your side, even if they sound friendly. Their job is to protect the company's interests, and a recorded statement is one of their most effective tools. By understanding what a recorded statement is in a car accident claim and how it can be used, you can make an informed decision about whether to give one and how to protect your rights.
If you are facing pressure to give a recorded statement, take a moment to breathe. You have options, and you do not have to go through the process alone. Whether you choose to handle the claim yourself or hire an attorney, being informed is your best defense.